Blogs & Press
What Should I Know About Florida Homeowners Insurance?
A clear, local expert breakdown from the Meyer Lucas Team on what buyers should expect with Florida insurance.
If you are moving to Palm Beach County, Jupiter, or anywhere along the South Florida coast, homeowners insurance works a little differently here. The combination of coastal exposure, storm risk, and rising construction costs means buyers need to understand how policies are structured and what to expect before closing. Here are the key things to keep in mind.
Holly Meyer Lucas also spoke with The New York Times about rising insurance costs. Read about the feature here.
Florida policies have a few features buyers from other states may not expect, including a separate hurricane deductible, flood coverage that is sold as its own policy, and rules tied to roof age. Understanding what your future home needs can help you budget more accurately from the start.
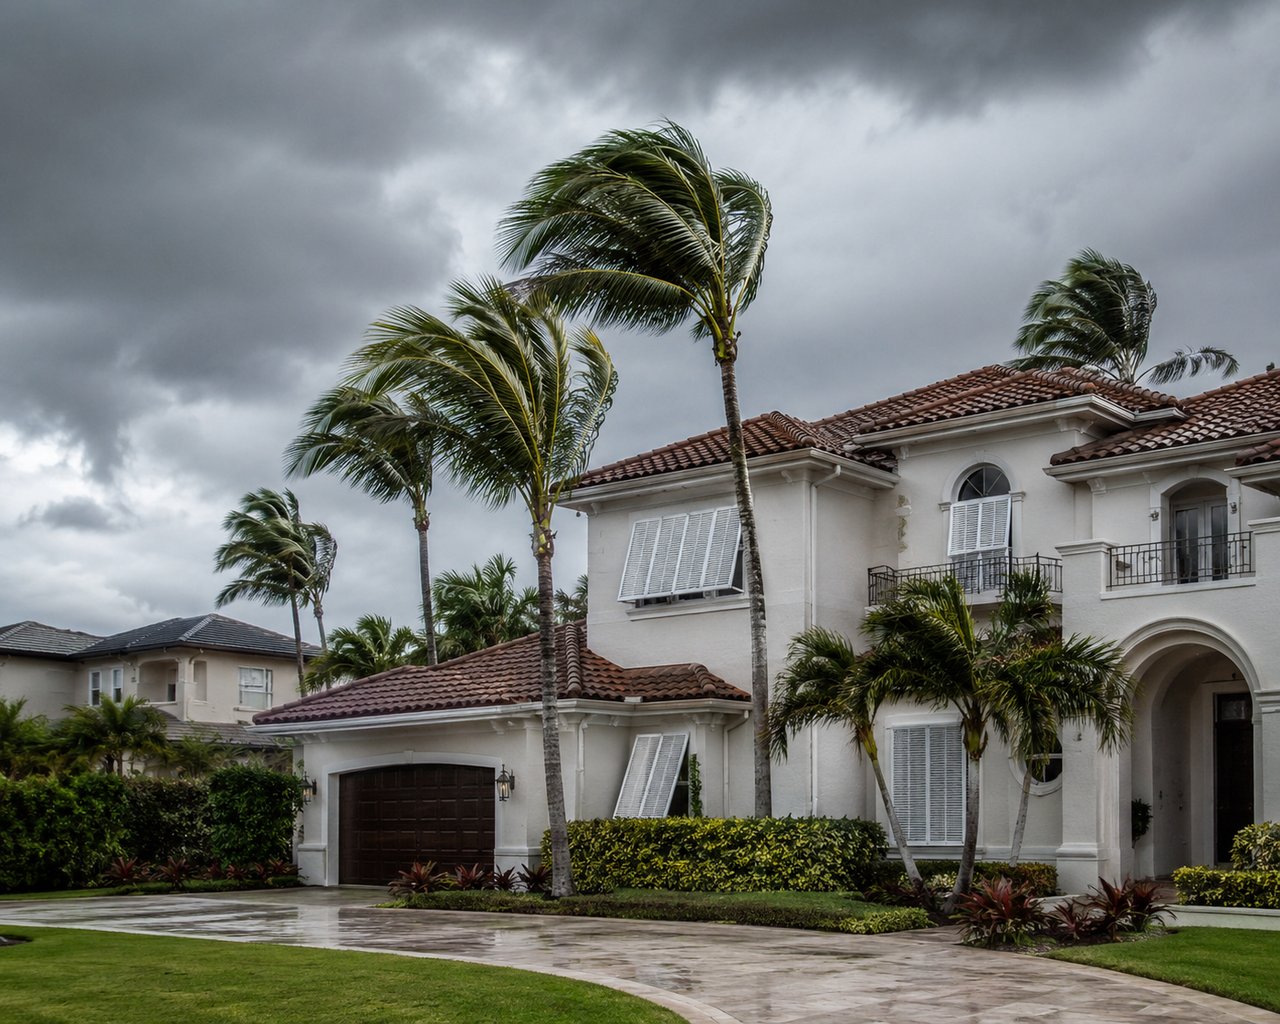
Wind and hurricane coverage are major factors. Florida policies carry a separate hurricane deductible, and Florida law requires insurers to offer options of $500 or 2, 5 or 10 percent of the dwelling coverage. Homes with documented wind mitigation features, such as impact-resistant windows and doors or a hip roof, can qualify for discounts on the wind portion of the premium after a wind mitigation inspection, according to Citizens Property Insurance.
Flood insurance is not automatically included. Under Florida law, insurers must tell homeowners in writing that a standard homeowners policy does not cover flood damage. Citizens is phasing in a flood insurance requirement for its policyholders, with most required to carry it by January 1, 2027. Your lender and your insurance provider will help determine what is required based on the property address.
Roof age matters in Florida. Under state law, an insurer can't refuse to write or renew a homeowners policy solely because the roof is less than 15 years old. For a roof 15 years or older, the homeowner can have it inspected, and the insurer can't refuse coverage based on age alone if the inspection shows at least five years of useful life left. This is why roof condition is one of the most important things buyers review during inspections.
Shopping policies is normal. Citizens encourages consumers to review deductibles with their agent when comparing coverage, and points them to the Office of Insurance Regulation's CHOICES tool for comparative homeowners rates by county. Local insurance brokers who specialize in South Florida properties can be a huge help.
The biggest tip is to start the conversation early. The Meyer Lucas Team works hand in hand with lenders, inspectors, and insurance pros to help you understand what coverage your new home will need. Florida insurance may look different from what you are used to, but with the right guidance it becomes a simple part of the buying process and gives you confidence that your investment is protected in one of the most beautiful coastal regions in the country.
🏡 We serve buyers and sellers in: Jupiter • Palm Beach • Palm Beach Gardens • Tequesta • Stuart • Hobe Sound • Palm City • North Palm Beach • Juno Beach
Let’s make your next move your best one!
📞 Call or Text: 561-406-5228
📩 Email: [email protected]
🌐 Learn more and meet the team: meyerlucas.com
🔍 See homes for sale: Home Search
Follow us for home tips, listings, and behind-the-scenes agent content:
📸 Instagram: @meyer.lucas.team
📘 Facebook: Meyer Lucas Group
🎥 TikTok: @meyer.lucas.team
💼 LinkedIn: Meyer Lucas Team
📅 Events: Facebook Events
📍 Let the top producing, award-winning Meyer Lucas Team in Jupiter, Florida help you buy or sell with confidence.
Mon - Fri, 9 am - 6 pm 1515 South Cypress Dr Jupiter FL 33469
Mon - Fri, 9 am - 6 pm 1515 South Cypress Dr Jupiter FL 33469